
ASTRO BOY
2026.02.17.
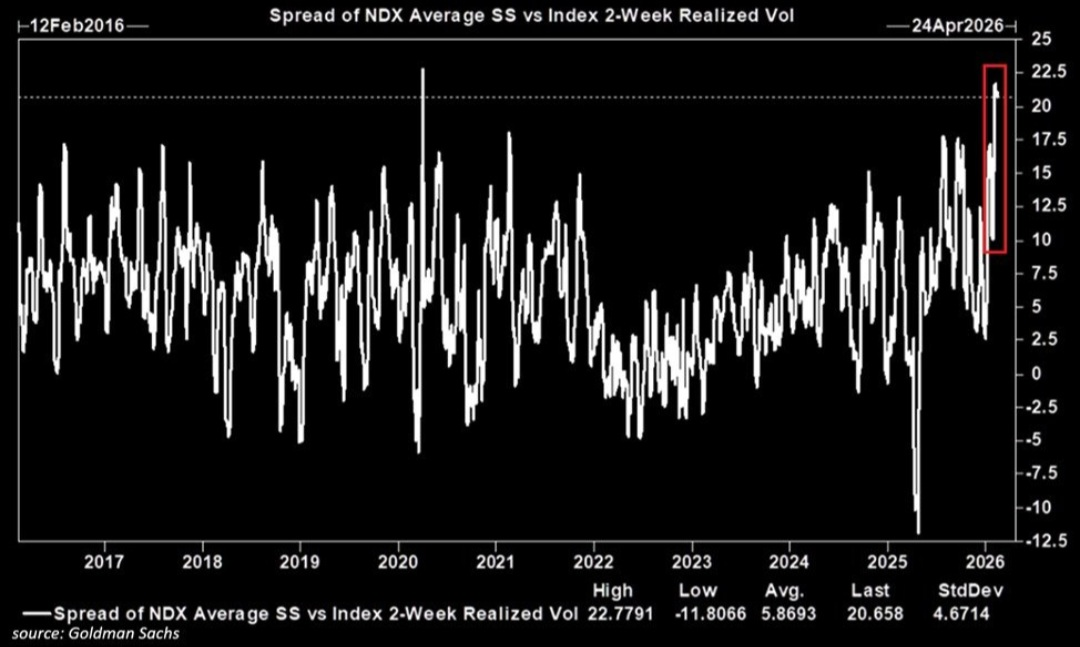
Market volatility is surging beneath the surface:
The spread between average single-stock 2-week volatility and the Nasdaq 100's volatility is up to 20.7 points, the highest since 2020.
This measures how much individual stocks are moving compared to the index, meaning the wider the spread, the more extreme the moves under the surface.
This spread has doubled over the last month, now 3 times higher than 4-year average.
Furthermore, the 3-month implied volatility spread between single stocks and the Nasdaq 100 is up to 18.4 points, the highest in at least 5 years.
By comparison, during the April 2025 sell-off, expected volatility stood at 11.0 points.
This means the market is pricing in continued single-stock stress.
Despite the broad market looking calm, volatility is severe in many parts of this market.

14

0

공유하기
모든 댓글
아직 댓글이 없습니다.

댓글을 작성하려면 로그인하세요.